We have been working in the field of tax and commercial consultancy since 1998. We analyse the situation of your business, diagnose the issues and provide solutions. We specialise in resolving problems arising from tax and commercial law.
We resolve commercial and tax disputes, attend to tax inspections, plan and advise on company transfers, and plan company restructuring processes, always using the most up-to-date tax planning tools. We provide comprehensive advice to individuals, startups, small and large companies, family groups and family offices.
Your peace of mind is our goal and transparency are our value. That is why we offer you all our knowledge and professionalism for all aspects relating to legal, economic, financial and tax areas. In a confidential and accessible manner.
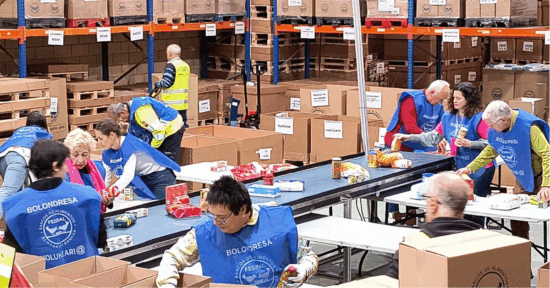
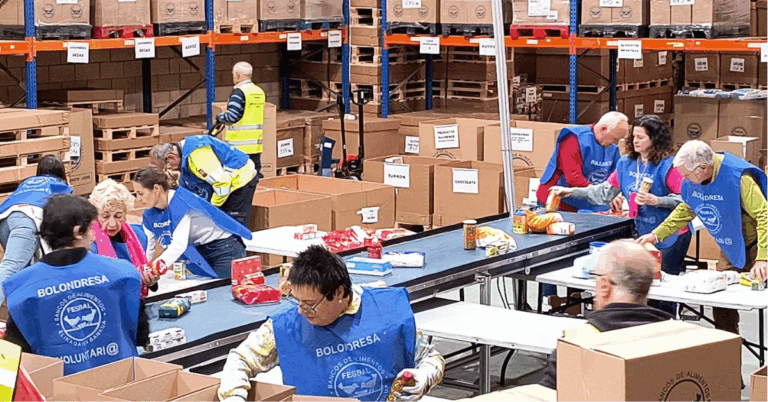
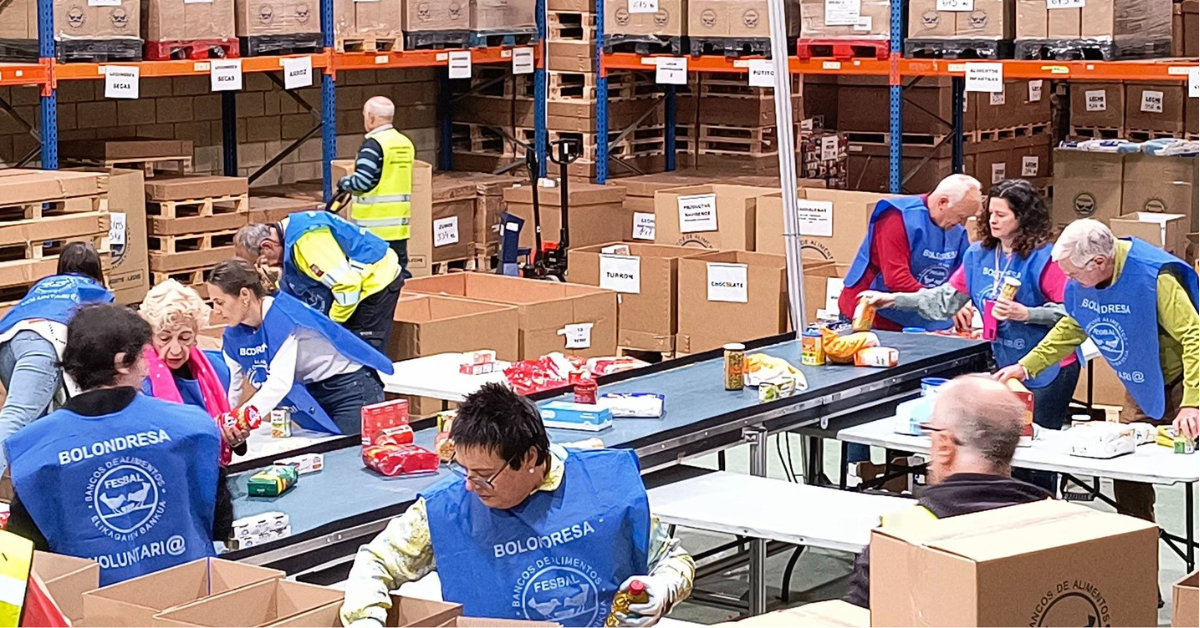
Euskaltax has participated once again in the annual Bizkaia Food Bank donation campaign, an initiative that celebrated its 30th anniversary this year and chose “We give it our all” as its...
array(14) {
["id"]=>
int(19810)
["type"]=>
string(4) "post"
["title"]=>
string(65) "Euskaltax participates in the Bizkaia Food Bank donation campaign"
["link"]=>
string(119) "https://www.euskaltax.com/en/actualidad/uncategorized/euskaltax-participates-in-the-bizkaia-food-bank-donation-campaign"
["excerpt"]=>
string(0) ""
["pseudo_excerpt"]=>
string(194) "Euskaltax has participated once again in the annual Bizkaia Food Bank donation campaign, an initiative that celebrated its 30th anniversary this year and chose “We give it our all” as its..."
["content"]=>
string(2704) "
With regard to the approval in the Historical Territory of Gipuzkoa of Provincial Law 1/2023, of 17 January, approving certain modifications for the year 2023, we have prepared an informative note detailing the main modifications introduced, some of which are effective as of 2021 and 2022.
Among the various tax changes, some of the extraordinary measures introduced to alleviate the effects of the energy crisis, the rise in prices and the war in Ukraine are extended exclusively for the year 2022, for example, (i) in personal income tax, the reduction percentages for deductible expenses for the determination of net income in the simplified form of the direct estimation method are extended, and (ii) in corporate income tax, the reduction in the tax base foreseen for micro-companies as tax compensation for the difficulties inherent to their size is maintained at 15%.
On the other hand, some of the Covid-19 measures introduced in previous years are established on a permanent basis, aimed at making some of the requirements for certain tax incentives more flexible, specifically, (i) in the area of personal income tax, the requirements for the deduction for the participation of workers in the employing entity or for the incorporation of entities by workers have become more flexible, and (ii) in corporate income tax, in particular with regard to Article 64Bis (deduction for financing R&D&I projects), as regards the extraordinary deadline for formalising the contract and the cases in which it may be modified, subject to prior notification to the tax authorities.
In addition, the formula for calculating values and assets not assigned to economic activities in relation to total assets is expressly included in the Corporate Income Tax, among others, in relation to asset-holding companies.
And, in Wealth Tax, with regard to the exemption of holdings in business entities, (i) the perimeter of the family group is extended to fourth-degree relatives in the case of a joint holding of 20% and (ii) two new cases of exemption are established for those cases in which the qualifying holding for access to the exemption has been reduced (5% or 20% joint holding).
The Nefab Group, through Nefab S.A.U., Spain, has acquired Embalajes Echeberria Soluciones de Embalaje, a company based in Vitoria-Gasteiz specializing in complete customized packaging solutions and...
array(14) {
["id"]=>
int(19783)
["type"]=>
string(4) "post"
["title"]=>
string(89) "Euskaltax acts as legal advisor to Embalajes Echeberria in the acquisition by NEFAB Group"
["link"]=>
string(156) "https://www.euskaltax.com/en/actualidad/circulares-informativas-en/euskaltax-acts-as-legal-advisor-to-embalajes-echeberria-in-the-acquisition-by-nefab-group"
["excerpt"]=>
string(0) ""
["pseudo_excerpt"]=>
string(201) "The Nefab Group, through Nefab S.A.U., Spain, has acquired Embalajes Echeberria Soluciones de Embalaje, a company based in Vitoria-Gasteiz specializing in complete customized packaging solutions and..."
["content"]=>
string(2704) "
With regard to the approval in the Historical Territory of Gipuzkoa of Provincial Law 1/2023, of 17 January, approving certain modifications for the year 2023, we have prepared an informative note detailing the main modifications introduced, some of which are effective as of 2021 and 2022.
Among the various tax changes, some of the extraordinary measures introduced to alleviate the effects of the energy crisis, the rise in prices and the war in Ukraine are extended exclusively for the year 2022, for example, (i) in personal income tax, the reduction percentages for deductible expenses for the determination of net income in the simplified form of the direct estimation method are extended, and (ii) in corporate income tax, the reduction in the tax base foreseen for micro-companies as tax compensation for the difficulties inherent to their size is maintained at 15%.
On the other hand, some of the Covid-19 measures introduced in previous years are established on a permanent basis, aimed at making some of the requirements for certain tax incentives more flexible, specifically, (i) in the area of personal income tax, the requirements for the deduction for the participation of workers in the employing entity or for the incorporation of entities by workers have become more flexible, and (ii) in corporate income tax, in particular with regard to Article 64Bis (deduction for financing R&D&I projects), as regards the extraordinary deadline for formalising the contract and the cases in which it may be modified, subject to prior notification to the tax authorities.
In addition, the formula for calculating values and assets not assigned to economic activities in relation to total assets is expressly included in the Corporate Income Tax, among others, in relation to asset-holding companies.
And, in Wealth Tax, with regard to the exemption of holdings in business entities, (i) the perimeter of the family group is extended to fourth-degree relatives in the case of a joint holding of 20% and (ii) two new cases of exemption are established for those cases in which the qualifying holding for access to the exemption has been reduced (5% or 20% joint holding).
On April 22, 2025, Provincial Law 2/2025, of April 9, was published in the BOB approving measures for the fiscal review of the tax system of the Historical Territory of Bizkaia, introducing...
array(14) {
["id"]=>
int(19785)
["type"]=>
string(4) "post"
["title"]=>
string(129) "Provincial Law 2/2025, of April 9, approving measures for the tax review of the tax system of the Historical Territory of Bizkaia"
["link"]=>
string(193) "https://www.euskaltax.com/en/actualidad/novedades-legislativas-en/provincial-law-2-2025-of-april-9-approving-measures-for-the-tax-review-of-the-tax-system-of-the-historical-territory-of-bizkaia"
["excerpt"]=>
string(0) ""
["pseudo_excerpt"]=>
string(192) "On April 22, 2025, Provincial Law 2/2025, of April 9, was published in the BOB approving measures for the fiscal review of the tax system of the Historical Territory of Bizkaia, introducing..."
["content"]=>
string(2704) "
With regard to the approval in the Historical Territory of Gipuzkoa of Provincial Law 1/2023, of 17 January, approving certain modifications for the year 2023, we have prepared an informative note detailing the main modifications introduced, some of which are effective as of 2021 and 2022.
Among the various tax changes, some of the extraordinary measures introduced to alleviate the effects of the energy crisis, the rise in prices and the war in Ukraine are extended exclusively for the year 2022, for example, (i) in personal income tax, the reduction percentages for deductible expenses for the determination of net income in the simplified form of the direct estimation method are extended, and (ii) in corporate income tax, the reduction in the tax base foreseen for micro-companies as tax compensation for the difficulties inherent to their size is maintained at 15%.
On the other hand, some of the Covid-19 measures introduced in previous years are established on a permanent basis, aimed at making some of the requirements for certain tax incentives more flexible, specifically, (i) in the area of personal income tax, the requirements for the deduction for the participation of workers in the employing entity or for the incorporation of entities by workers have become more flexible, and (ii) in corporate income tax, in particular with regard to Article 64Bis (deduction for financing R&D&I projects), as regards the extraordinary deadline for formalising the contract and the cases in which it may be modified, subject to prior notification to the tax authorities.
In addition, the formula for calculating values and assets not assigned to economic activities in relation to total assets is expressly included in the Corporate Income Tax, among others, in relation to asset-holding companies.
And, in Wealth Tax, with regard to the exemption of holdings in business entities, (i) the perimeter of the family group is extended to fourth-degree relatives in the case of a joint holding of 20% and (ii) two new cases of exemption are established for those cases in which the qualifying holding for access to the exemption has been reduced (5% or 20% joint holding).
Royal Decree-Law 4/2025, of April 8, establishes urgent measures with the aim of addressing the tariff threat and promoting economic recovery. Among the main new developments are the extension of the...
array(14) {
["id"]=>
int(19787)
["type"]=>
string(4) "post"
["title"]=>
string(58) "The cause for dissolution due to losses is suspended again"
["link"]=>
string(125) "https://www.euskaltax.com/en/actualidad/circulares-informativas-en/the-cause-for-dissolution-due-to-losses-is-suspended-again"
["excerpt"]=>
string(0) ""
["pseudo_excerpt"]=>
string(202) "Royal Decree-Law 4/2025, of April 8, establishes urgent measures with the aim of addressing the tariff threat and promoting economic recovery. Among the main new developments are the extension of the..."
["content"]=>
string(2704) "
With regard to the approval in the Historical Territory of Gipuzkoa of Provincial Law 1/2023, of 17 January, approving certain modifications for the year 2023, we have prepared an informative note detailing the main modifications introduced, some of which are effective as of 2021 and 2022.
Among the various tax changes, some of the extraordinary measures introduced to alleviate the effects of the energy crisis, the rise in prices and the war in Ukraine are extended exclusively for the year 2022, for example, (i) in personal income tax, the reduction percentages for deductible expenses for the determination of net income in the simplified form of the direct estimation method are extended, and (ii) in corporate income tax, the reduction in the tax base foreseen for micro-companies as tax compensation for the difficulties inherent to their size is maintained at 15%.
On the other hand, some of the Covid-19 measures introduced in previous years are established on a permanent basis, aimed at making some of the requirements for certain tax incentives more flexible, specifically, (i) in the area of personal income tax, the requirements for the deduction for the participation of workers in the employing entity or for the incorporation of entities by workers have become more flexible, and (ii) in corporate income tax, in particular with regard to Article 64Bis (deduction for financing R&D&I projects), as regards the extraordinary deadline for formalising the contract and the cases in which it may be modified, subject to prior notification to the tax authorities.
In addition, the formula for calculating values and assets not assigned to economic activities in relation to total assets is expressly included in the Corporate Income Tax, among others, in relation to asset-holding companies.
And, in Wealth Tax, with regard to the exemption of holdings in business entities, (i) the perimeter of the family group is extended to fourth-degree relatives in the case of a joint holding of 20% and (ii) two new cases of exemption are established for those cases in which the qualifying holding for access to the exemption has been reduced (5% or 20% joint holding).
Euskaltax has appointed Asier Guezuraga as Of Counsel partner at the firm. He will now be responsible for the firm’s strategic planning, relieving him of the recurring advisory functions he has...
array(14) {
["id"]=>
int(19793)
["type"]=>
string(4) "post"
["title"]=>
string(57) "Asier Guezuraga appointed Of Counsel partner at Euskaltax"
["link"]=>
string(124) "https://www.euskaltax.com/en/actualidad/circulares-informativas-en/asier-guezuraga-appointed-of-counsel-partner-at-euskaltax"
["excerpt"]=>
string(0) ""
["pseudo_excerpt"]=>
string(198) "Euskaltax has appointed Asier Guezuraga as Of Counsel partner at the firm. He will now be responsible for the firm’s strategic planning, relieving him of the recurring advisory functions he has..."
["content"]=>
string(2704) "
With regard to the approval in the Historical Territory of Gipuzkoa of Provincial Law 1/2023, of 17 January, approving certain modifications for the year 2023, we have prepared an informative note detailing the main modifications introduced, some of which are effective as of 2021 and 2022.
Among the various tax changes, some of the extraordinary measures introduced to alleviate the effects of the energy crisis, the rise in prices and the war in Ukraine are extended exclusively for the year 2022, for example, (i) in personal income tax, the reduction percentages for deductible expenses for the determination of net income in the simplified form of the direct estimation method are extended, and (ii) in corporate income tax, the reduction in the tax base foreseen for micro-companies as tax compensation for the difficulties inherent to their size is maintained at 15%.
On the other hand, some of the Covid-19 measures introduced in previous years are established on a permanent basis, aimed at making some of the requirements for certain tax incentives more flexible, specifically, (i) in the area of personal income tax, the requirements for the deduction for the participation of workers in the employing entity or for the incorporation of entities by workers have become more flexible, and (ii) in corporate income tax, in particular with regard to Article 64Bis (deduction for financing R&D&I projects), as regards the extraordinary deadline for formalising the contract and the cases in which it may be modified, subject to prior notification to the tax authorities.
In addition, the formula for calculating values and assets not assigned to economic activities in relation to total assets is expressly included in the Corporate Income Tax, among others, in relation to asset-holding companies.
And, in Wealth Tax, with regard to the exemption of holdings in business entities, (i) the perimeter of the family group is extended to fourth-degree relatives in the case of a joint holding of 20% and (ii) two new cases of exemption are established for those cases in which the qualifying holding for access to the exemption has been reduced (5% or 20% joint holding).
On November 19, the Provincial Council of Bizkaia published a Draft Provincial Law introducing certain measures for the tax review of the tax system, affecting different taxes in the tax system of...
array(14) {
["id"]=>
int(19795)
["type"]=>
string(4) "post"
["title"]=>
string(127) "Preliminary draft Provincial Law approving measures for the tax review of the tax system of the Historical Territory of Bizkaia"
["link"]=>
string(193) "https://www.euskaltax.com/en/actualidad/novedades-legislativas-en/preliminary-draft-provincial-law-approving-measures-for-the-tax-review-of-the-tax-system-of-the-historical-territory-of-bizkaia"
["excerpt"]=>
string(0) ""
["pseudo_excerpt"]=>
string(199) "On November 19, the Provincial Council of Bizkaia published a Draft Provincial Law introducing certain measures for the tax review of the tax system, affecting different taxes in the tax system of..."
["content"]=>
string(2704) "
With regard to the approval in the Historical Territory of Gipuzkoa of Provincial Law 1/2023, of 17 January, approving certain modifications for the year 2023, we have prepared an informative note detailing the main modifications introduced, some of which are effective as of 2021 and 2022.
Among the various tax changes, some of the extraordinary measures introduced to alleviate the effects of the energy crisis, the rise in prices and the war in Ukraine are extended exclusively for the year 2022, for example, (i) in personal income tax, the reduction percentages for deductible expenses for the determination of net income in the simplified form of the direct estimation method are extended, and (ii) in corporate income tax, the reduction in the tax base foreseen for micro-companies as tax compensation for the difficulties inherent to their size is maintained at 15%.
On the other hand, some of the Covid-19 measures introduced in previous years are established on a permanent basis, aimed at making some of the requirements for certain tax incentives more flexible, specifically, (i) in the area of personal income tax, the requirements for the deduction for the participation of workers in the employing entity or for the incorporation of entities by workers have become more flexible, and (ii) in corporate income tax, in particular with regard to Article 64Bis (deduction for financing R&D&I projects), as regards the extraordinary deadline for formalising the contract and the cases in which it may be modified, subject to prior notification to the tax authorities.
In addition, the formula for calculating values and assets not assigned to economic activities in relation to total assets is expressly included in the Corporate Income Tax, among others, in relation to asset-holding companies.
And, in Wealth Tax, with regard to the exemption of holdings in business entities, (i) the perimeter of the family group is extended to fourth-degree relatives in the case of a joint holding of 20% and (ii) two new cases of exemption are established for those cases in which the qualifying holding for access to the exemption has been reduced (5% or 20% joint holding).
On September 26, 2024, the Provincial Council of Bizkaia published a preliminary draft Provincial Law introducing certain tax measures affecting various taxes, with different effects, generally...
array(14) {
["id"]=>
int(19797)
["type"]=>
string(4) "post"
["title"]=>
string(55) "Preliminary draft Provincial Law approving tax measures"
["link"]=>
string(122) "https://www.euskaltax.com/en/actualidad/circulares-informativas-en/preliminary-draft-provincial-law-approving-tax-measures"
["excerpt"]=>
string(0) ""
["pseudo_excerpt"]=>
string(196) "On September 26, 2024, the Provincial Council of Bizkaia published a preliminary draft Provincial Law introducing certain tax measures affecting various taxes, with different effects, generally..."
["content"]=>
string(2704) "
With regard to the approval in the Historical Territory of Gipuzkoa of Provincial Law 1/2023, of 17 January, approving certain modifications for the year 2023, we have prepared an informative note detailing the main modifications introduced, some of which are effective as of 2021 and 2022.
Among the various tax changes, some of the extraordinary measures introduced to alleviate the effects of the energy crisis, the rise in prices and the war in Ukraine are extended exclusively for the year 2022, for example, (i) in personal income tax, the reduction percentages for deductible expenses for the determination of net income in the simplified form of the direct estimation method are extended, and (ii) in corporate income tax, the reduction in the tax base foreseen for micro-companies as tax compensation for the difficulties inherent to their size is maintained at 15%.
On the other hand, some of the Covid-19 measures introduced in previous years are established on a permanent basis, aimed at making some of the requirements for certain tax incentives more flexible, specifically, (i) in the area of personal income tax, the requirements for the deduction for the participation of workers in the employing entity or for the incorporation of entities by workers have become more flexible, and (ii) in corporate income tax, in particular with regard to Article 64Bis (deduction for financing R&D&I projects), as regards the extraordinary deadline for formalising the contract and the cases in which it may be modified, subject to prior notification to the tax authorities.
In addition, the formula for calculating values and assets not assigned to economic activities in relation to total assets is expressly included in the Corporate Income Tax, among others, in relation to asset-holding companies.
And, in Wealth Tax, with regard to the exemption of holdings in business entities, (i) the perimeter of the family group is extended to fourth-degree relatives in the case of a joint holding of 20% and (ii) two new cases of exemption are established for those cases in which the qualifying holding for access to the exemption has been reduced (5% or 20% joint holding).
September 30 is the deadline for claiming a refund of input VAT paid in the previous year by entrepreneurs or professionals not established in the territory where the tax applies (Article 31.4 of the...
array(14) {
["id"]=>
int(19799)
["type"]=>
string(4) "post"
["title"]=>
string(58) "Deadline for claiming input VAT by non-established persons"
["link"]=>
string(112) "https://www.euskaltax.com/en/actualidad/uncategorized/deadline-for-claiming-input-vat-by-non-established-persons"
["excerpt"]=>
string(0) ""
["pseudo_excerpt"]=>
string(202) "September 30 is the deadline for claiming a refund of input VAT paid in the previous year by entrepreneurs or professionals not established in the territory where the tax applies (Article 31.4 of the..."
["content"]=>
string(2704) "
With regard to the approval in the Historical Territory of Gipuzkoa of Provincial Law 1/2023, of 17 January, approving certain modifications for the year 2023, we have prepared an informative note detailing the main modifications introduced, some of which are effective as of 2021 and 2022.
Among the various tax changes, some of the extraordinary measures introduced to alleviate the effects of the energy crisis, the rise in prices and the war in Ukraine are extended exclusively for the year 2022, for example, (i) in personal income tax, the reduction percentages for deductible expenses for the determination of net income in the simplified form of the direct estimation method are extended, and (ii) in corporate income tax, the reduction in the tax base foreseen for micro-companies as tax compensation for the difficulties inherent to their size is maintained at 15%.
On the other hand, some of the Covid-19 measures introduced in previous years are established on a permanent basis, aimed at making some of the requirements for certain tax incentives more flexible, specifically, (i) in the area of personal income tax, the requirements for the deduction for the participation of workers in the employing entity or for the incorporation of entities by workers have become more flexible, and (ii) in corporate income tax, in particular with regard to Article 64Bis (deduction for financing R&D&I projects), as regards the extraordinary deadline for formalising the contract and the cases in which it may be modified, subject to prior notification to the tax authorities.
In addition, the formula for calculating values and assets not assigned to economic activities in relation to total assets is expressly included in the Corporate Income Tax, among others, in relation to asset-holding companies.
And, in Wealth Tax, with regard to the exemption of holdings in business entities, (i) the perimeter of the family group is extended to fourth-degree relatives in the case of a joint holding of 20% and (ii) two new cases of exemption are established for those cases in which the qualifying holding for access to the exemption has been reduced (5% or 20% joint holding).